Originally released in The Interline’s AI Report 2026, this executive interview with Swap Commerce is one of a 17-part series that sees The Interline quiz executives from companies who have either introduced new AI solutions or added meaningful new AI capabilities into their existing platforms.
For more exclusive interviews, stories and opinions from different industry perspectives, and real survey feedback from voices from every level of fashion, download The AI Report 2026.
We’re observing a big disconnect (in both our own fashion-only data and in wider benchmarks from other sources) between the increasing capability and reliability of AI, in both a general sense and in discrete applications, and the lack of trust that end users place in its outputs. What do you think trust in AI looks like, and what’s the right rubric for measuring it?
Trust in AI is being measured wrong, the same way value in AI is being measured wrong. The industry keeps running surveys asking people if they trust AI, and people keep saying no. But survey sentiment is an input metric. It tells you what people say, not what they do.
The real rubric for trust is behavior. Does the shopper act on what the agent recommends? Do they add it to cart? Do they buy it? Do they come back and let the agent do more next time? That’s trust, revealed. And by that measure the gap looks very different. On virtual try-on, 58% of sessions end in add-to-cart and 20% convert. People who “don’t trust AI” are handing it their purchase decisions every day, because in that moment the AI is useful and accountable.
That last word is the whole game. Trust doesn’t come from accuracy in the abstract. It comes from accountability. The reason consumers are wary of AI outputs is that most AI they meet has no owner and no stake in being right. A generic model surfaces a product and disappears. Nobody the shopper has a relationship with stands behind it.
It’s also that a lot of the AI consumers have actually encountered is just bad. A chatbot bolted onto a checkout page that loops them in circles. A recommendation engine that ignores everything they looked at thirty seconds ago. Most of the skepticism out there isn’t irrational, it’s earned. People aren’t distrusting AI as a category, they’re distrusting the poorly implemented version of it they keep running into. That’s a quality problem, not an AI problem, and it sets a low bar that a well-built agent clears immediately.
Merchant-owned AI inverts that. When the agent is the brand’s agent, the brand’s name is on every recommendation and the reputation is on the line. That’s what makes the output trustworthy, not the size of the model. And it compounds. An agent that remembers your last search, knows your size, and gets the next recommendation right earns more trust on every visit. Trust isn’t a static score you measure once. It’s a relationship that deepens with first-party intent data, and it’s the hardest thing for a competitor to copy.
It’s important to understand the context and the mandate for applying AI to the existing eCommerce stack, because otherwise it runs the real risk of seeming like innovation for its own sake. What is it about the current storefront that you see as either in decline, or not carrying the weight it should be for creating unique consumer experiences? Fashion has invested a lot in improving the current paradigm, so there’s a lot of inertia at play when it comes to potentially supplementing or replacing it. What do you see as sufficiently broken that it justifies replacing it with an agentic model, before we get to the benefits of that new model?
Let me be precise about the diagnosis first. The storefront isn’t in decline. It’s hit its ceiling. That’s the more useful way to see it, because a ceiling is something you can’t optimize your way past, no matter how much you spend.
For twenty years fashion has taken the print catalogue and the store shelf, ported them to a screen, and made that port better. Better photography. Faster load times. Smarter search. Cleaner filtering. Better checkout, more payment options, one-click everything. All of it real, all of it expensive, and all of it improving the same underlying thing: a surface that displays product and waits.
That’s what’s broken. The storefront was built to display, not to sell. In a physical store there’s a salesperson who reads you, asks what the occasion is, pulls options, builds the look, handles “I’m not sure about the fit,” and closes. Moving online, we deleted that person and replaced them with a search bar and a filter menu, then called it self-service. We never digitized selling. We digitized the catalogue and left the shopper to do all the work of finding, deciding, and converting alone.
The proof is the one number nobody has been able to move. Since 2006 the average cart abandonment rate has climbed from 59.8% to roughly 70%, peaking at 72% in 2012 before it stabilized. It has barely shifted in almost twenty years, through every checkout improvement the industry has shipped. If checkout were the problem, better checkout would have fixed it. It didn’t, because the problem was never the last step. The storefront can’t read intent, can’t respond to it, and can’t guide. The shopper arrives ready to buy and the page just shows them things and hopes.
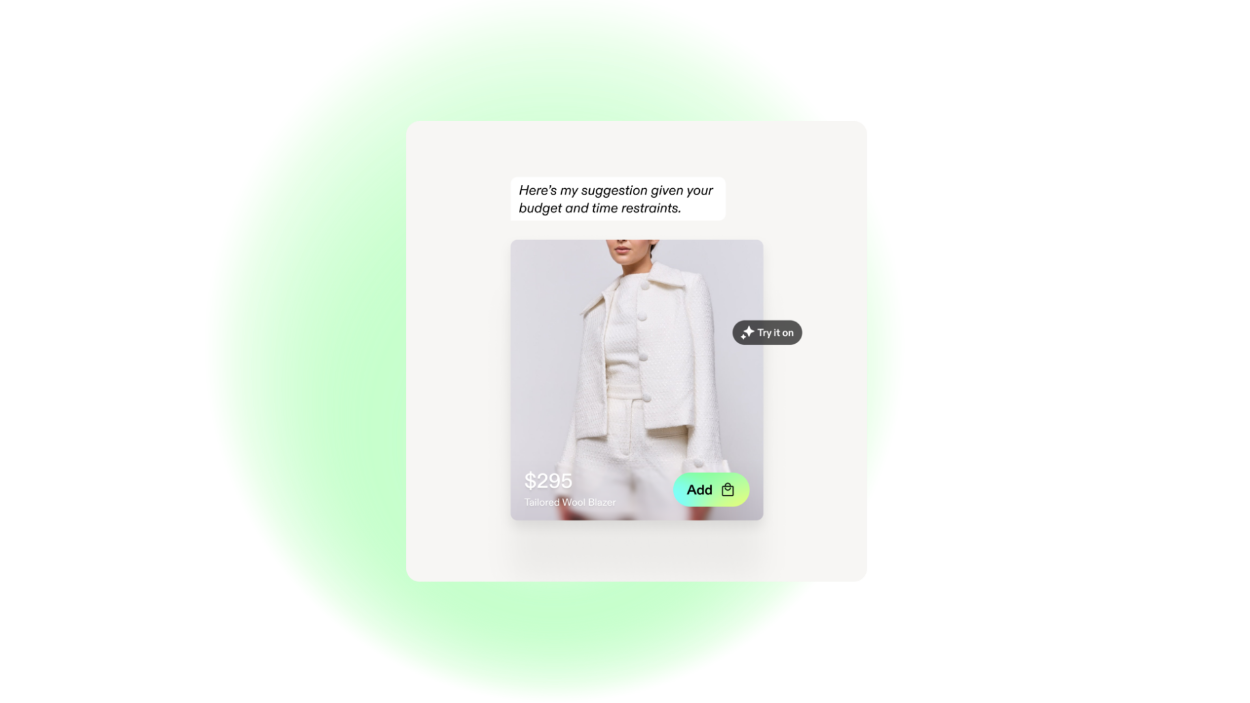
This is where the inertia actually costs you. The investments are real, but they’re marginal gains on a structurally capped model, which is the definition of diminishing returns. At some point the honest read is that the model itself is the constraint, not how well you execute it. You don’t fix a storefront built to display by displaying harder. You replace it. Agentic commerce swaps the catalogue you browse for a conversation that guides, which is the one thing the static page was never built to do.
It feels as though fashion has decided to judge AI by a different set of metrics to the way it judges other technology investments. We get a lot of “efficiency” and “productivity” with general purpose use cases, and even for specific disciplines like eCommerce the ROI yardsticks are still a little bit nebulous – things like time saved and “streamlined operations”. Given that we’re talking about storefronts here – one of the parts of fashion the most obsessed with indicators – how do you suggest companies measure the value of AI in concrete terms that align more closely with existing rubrics? And what trendlines do you see to suggest that those metrics are going in the right direction from here?
The metrics problem is self-inflicted, and it’s the easiest one to fix. Fashion has decided to grade AI on a curve. Other technology investments get held to revenue and margin. AI gets held to “efficiency” and “time saved,” which are the softest yardsticks in the building. So my first answer is simple: stop grading it on a curve. You already own a rubric for the storefront. Use that one.
Most brands measure inputs. Prompts run, hours saved, workflows streamlined. Those are activity metrics. They tell you the tool is being used, not that it’s working. They feel like progress and they justify nothing, because no CFO has ever approved a budget line on hours saved alone. The real test is the same scorecard you’d apply to any change you made to your primary commercial surface: conversion, average order value, retention, and margin. If an AI investment can’t be expressed in those four, it isn’t ready to be on the storefront.
The good news for an industry obsessed with indicators is that the agentic model reports cleanly into all four. Across the 20+ brands now running the Agentic Storefront we’re seeing the same pattern repeat: 2x conversion, 3x time on site, 22% higher monthly AOV, and 20% fewer returns. Note where those sit. Conversion and AOV are top line. Returns are pure margin, and in fashion returns are one of the largest cost centers there is, so a 20% reduction is a P&L event, not a satisfaction score. None of this requires a special AI dashboard. It lands in the reporting you already run.
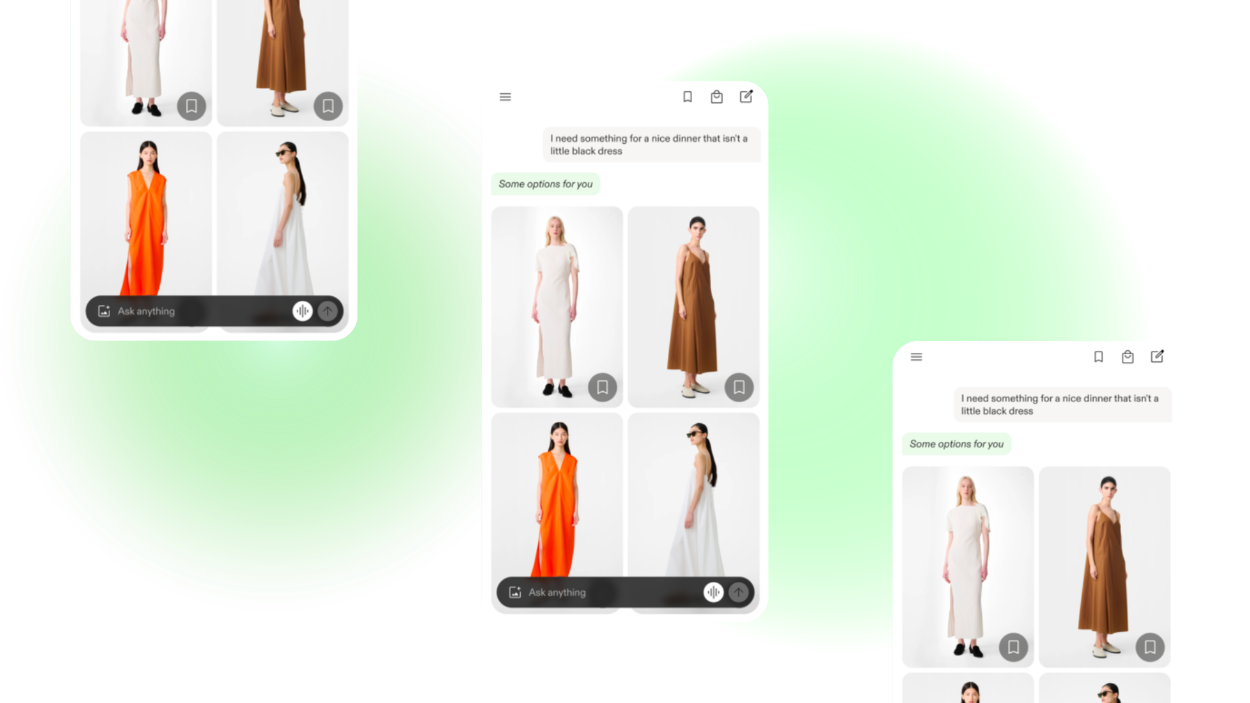
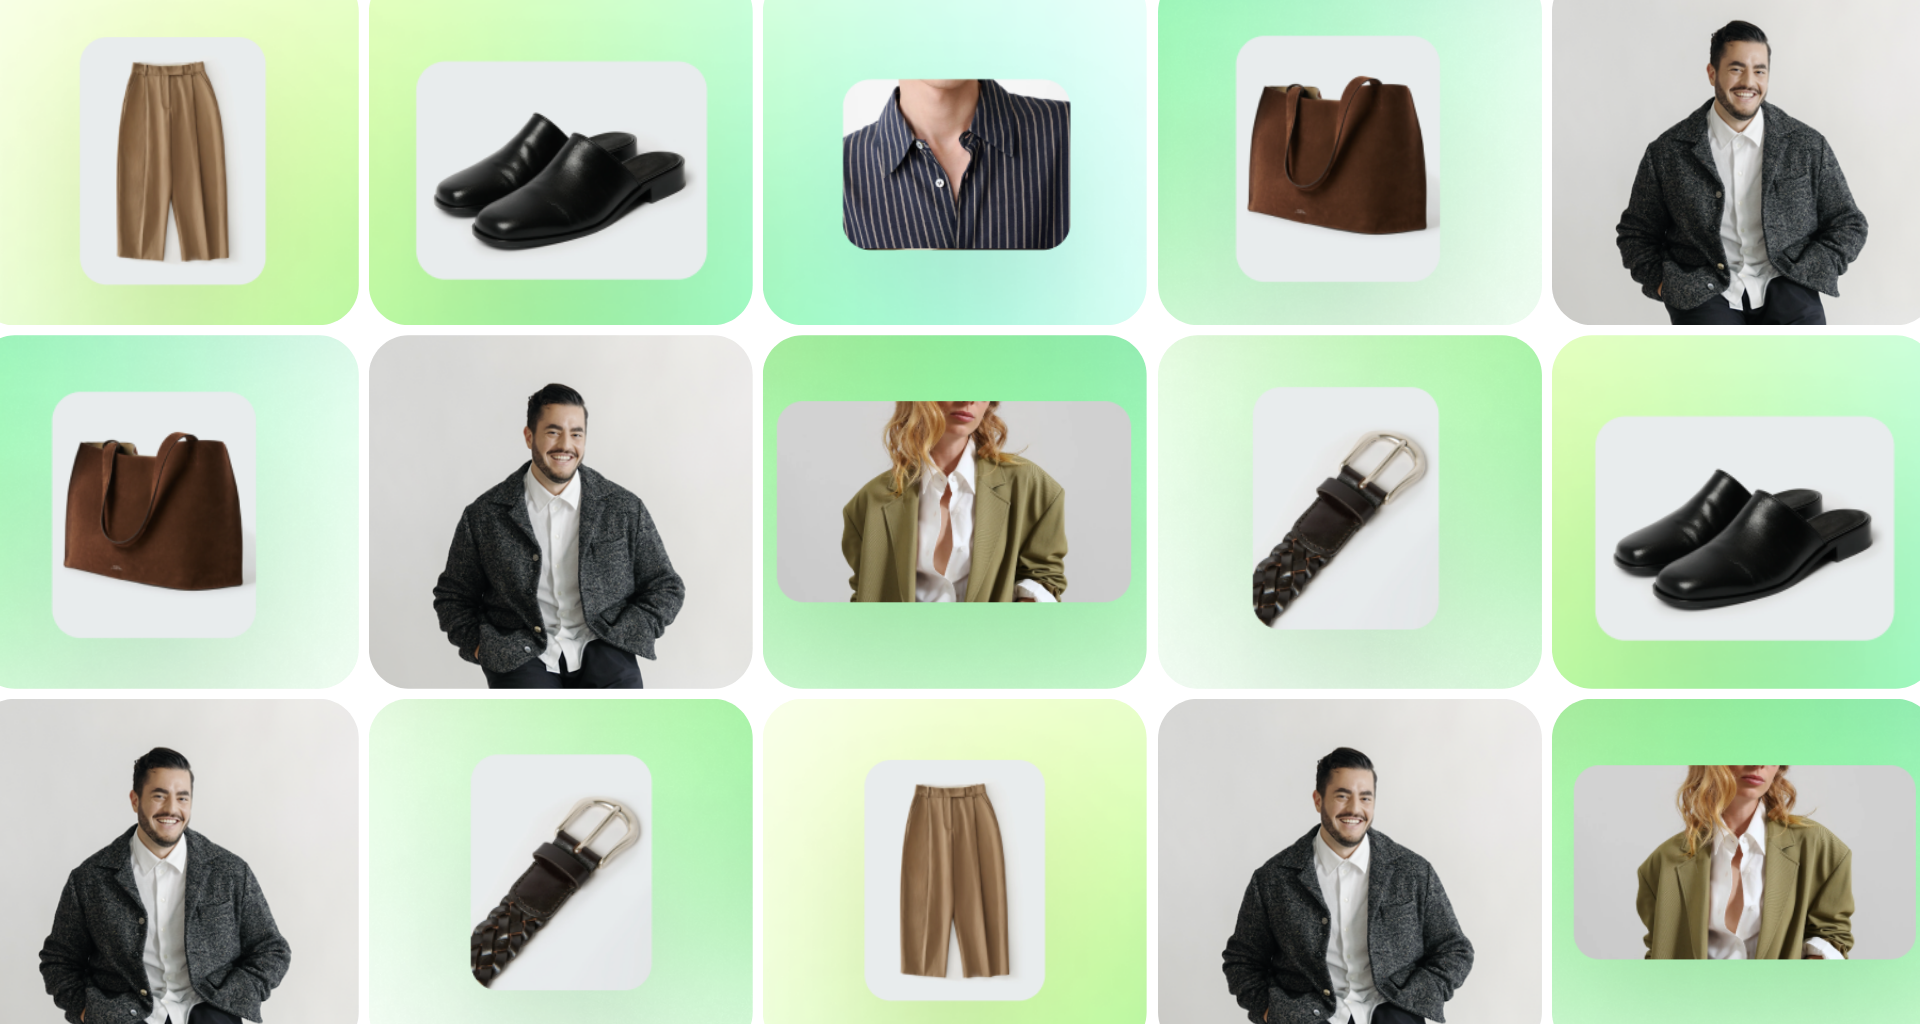
Virtual try-on is the cleanest example, because it isolates the behavior. 58% of try-on sessions end in add-to-cart and 20% convert to purchase. That’s not a productivity metric dressed up as value. That’s a shopper doing the one thing the whole storefront exists to make them do, at a rate a static product page has never come close to.
On the trendlines, here’s the part that matters most and gets missed. A static storefront performs the same on day one and day five hundred. We saw that in the abandonment number that wouldn’t move for twenty years. An agent does the opposite. It gets better with use, because every session is first-party intent data that sharpens the next recommendation. So the trendline inside a single brand isn’t flat, it’s up and to the right, and the gap between the agentic surface and the static one widens the longer it runs. That’s the inversion of everything fashion is used to from the static page.
Two more vectors point the same direction. At the category level, every brand that posts this lift resets the benchmark, so the metric moves industry-wide, not just account by account. And underneath all of it, the models keep getting more capable and cheaper every quarter, which means the margin on running an agent improves even if a brand changes nothing on its end. That’s the rare case where the technology gets better and less expensive at the same time. The numbers we’re posting today are the floor, not the ceiling.
We ran a series of interviews about agentic commerce across the end of last year and into the first half of this year. One sentiment that was consistent across all of them was the desire for AI to not end up being a point of normalisation – a horizon past which AI giants like Google and OpenAI wind up controlling the entire consumer relationship, and brand experiences wind up becoming even more homogeneous than they already are. Obviously Swap’s bet is on merchant-owned AI, but tell us why you see the current moment as such an important juncture for determining what the future relationship between brands and shoppers will look like.
Because defaults are being set right now, and defaults are almost impossible to claw back once they harden. Shopper behavior is still forming. Whether people learn to start their shopping inside a brand’s own experience or inside ChatGPT’s gets decided in the next year or two, not the next decade. After that it’s habit, and habit is path-dependent. So this isn’t a normal technology adoption curve where you can wait and buy in later at a better price. The thing being decided isn’t when you adopt. It’s who owns the customer when the dust settles.
Fashion should recognize this movie, because it has sat through it before. Every time a new layer inserted itself between brand and shopper, the brand lost ground and started paying rent. Wholesale and department stores owned the relationship for decades. Marketplaces did it again online, turning brands into SKUs competing on a shelf they didn’t control. Then Google became the front door, and brands ended up paying to show up for searches on their own name. Each step, the intermediary captured the relationship and the brand became a supplier to it. The AI giants are the next layer, and they’re the most total version yet, because they don’t just take a transaction cut or an ad tax. They take the conversation itself.
And their incentive is not your incentive. ChatGPT, Google, and Perplexity will happily surface products, but they are built to keep the shopper on their platform, not to convert that shopper for your brand. You become an answer inside someone else’s interface. That’s where the homogenization fear your interviewees kept raising actually comes from. It isn’t abstract. When your brand is reduced to a result in a neutral chat window, the medium flattens you. The brand world you spent decades and fortunes building, the photography, the voice, the feeling of the thing, collapses into a line of text that looks identical to every competitor’s line of text. A heritage house and a fast-fashion label render the same in a generic answer box. Everything that made you distinct gets stripped at the door.
Underneath all of it sits the part that compounds, which is the data. Whoever owns the conversation owns the first-party intent data, and that data is the asset that gets more valuable every day it accumulates. If the platform owns the agent, the platform learns across every brand and every shopper, gets smarter on your customers, and hands you nothing back. The asymmetry widens with time. They compound, you stay dependent, and the gap is unrecoverable because you can never go back and collect the signal you didn’t keep.
That’s the whole case for merchant-owned AI, and it’s why the timing is not negotiable. The brands that own their own agentic experience keep the relationship and keep the compounding data. The ones that outsource it to a platform are renting access to their own customers and training someone else’s model while they do it. The agent is going to be the primary way people shop. The only question on the table right now is whether that agent is yours or theirs, and that question does not stay open for long.
For a long time now, there’s been tension between the idea of “omnichannel,” that every touchpoint should lead to the same common trunk, and that shoppers prioritise familiarity and ease, and the idea that individual channels should be differentiated from one another by the experiences that only they can offer. You’re now inserting AI into that question, and it feels as though it could be applied to serve either vision – efficiency and normalisation, or uniqueness and experiential shopping. Which are you betting on, and why?
Uniqueness. Experiential, every time. But I’d push back on the premise a little, because the choice the question describes is a false one, and it only ever felt like a real tradeoff because of the technology we were stuck with.
Here’s why that tension existed in the first place. Sameness was cheap and differentiation was expensive. Building one templated experience and stamping it across every touchpoint was affordable and easy to keep consistent. Building something genuinely distinct per channel cost more, broke more, and drifted out of sync the moment you shipped it. So the industry defaulted to sameness, called it omnichannel, and dressed up a budget constraint as a customer-experience philosophy. The familiarity-and-ease argument was real, but it was also a convenient justification for the cheaper path.
And in doing that, fashion standardized the wrong layer. It made the front end uniform, the look and the interface, while letting the actual intelligence fragment into silos, where the app didn’t know what the store knew and neither knew what the site knew. That’s backwards. The thing that should be common across every touchpoint isn’t the interface. It’s the brand’s understanding of the shopper. The agent finally lets you put the consistency where it belongs. One brain that knows the customer everywhere, their size, their history, their taste, carried across every visit and every channel, and on top of that a surface free to be completely distinct in every moment. You get the familiarity and the ease, because the agent remembers you and removes friction. You also get the uniqueness, because the experience is no longer a template. The tradeoff dissolves. You stop choosing between the two and you get both.
And the reason I bet on the experiential side without hesitation is that it’s the one that actually moves the numbers, so this was never a vibes argument against an efficiency argument. The WILLY CHAVARRIA x adidas World Cup collection launched exclusively through an AI-powered Storefront and 2x’d the brand’s biggest ecommerce sales day ever on launch day. A culturally significant drop didn’t get a product page that looked like every other product page. It got an experience built for the moment, and the experience converted at a level the static surface had never produced. That’s the proof. Uniqueness isn’t the soft, expensive option you indulge at the cost of performance. It’s the thing that performs.
So the bet is simple. Efficiency was never actually the goal. Conversion was. The industry only reached for efficiency and normalisation because the static page couldn’t deliver anything else at scale. The agent can, which means the experiential path and the commercial path are now the same path. A major drop deserves more than a static product page, and now there’s a number that proves the brand can’t afford to give it one.
Last year, we asked technology executives whether they predicted AI would become more obvious, as a primary interface paradigm, or whether it would disappear into the background in the way that vital but invisible platforms like AWS and Azure have done. This year’s data suggests that the answer is both: fashion professionals that use AI interact with it as both the engine and the steering wheel. But we also see that, for a lot of companies, both kinds of applications are still largely in the scoping or refined-pilot stage. What do you see being the trigger for deeper adoption and wider roll-out?
Both being true is exactly why it’s stuck. When AI is just a feature in the background, rolling it out is a small bet you can make quietly. When it’s both the engine and the steering wheel, the roll-out decision is no longer about a tool. It’s a decision about your primary commercial surface, the thing your whole business runs through. Decisions that big don’t move on promise or on potential. They move on proof. So the scoping-and-pilot phase isn’t hesitation. It’s an industry waiting for the one thing that makes the call obvious.
And the trigger is specific. It’s the first time AI moves a number that shows up on the P&L. Not before. Pilots stay pilots for a structural reason, and it’s the same input-versus-output problem that runs through everything we’ve talked about. Pilots get scoped by innovation teams and judged on innovation metrics, engagement, learnings, “promising signals.” Those metrics are real and they justify nothing, because no one reallocates a commercial budget on learnings. The moment the same initiative produces conversion, AOV, or margin, the ownership of it changes hands. It stops being an experiment the innovation team is running on the side and becomes infrastructure the commercial team depends on to hit its number. That handoff, from innovation metric to commercial metric, from a thing being trialed to a thing being relied on, is the actual mechanism that turns a pilot into a roll-out. Everything before it is scoping. Everything after it is scale.
Usually it takes one undeniable moment to force that handoff. For us that moment has a name. The WILLY CHAVARRIA x adidas World Cup collection launched exclusively through an agentic Storefront and 2x’d the brand’s biggest ecommerce sales day ever on launch. You cannot un-see a number like that. It reframes the internal conversation in a single step, from “should we test this” to “why is our next drop not on this.” A refined pilot can be debated for another two quarters. A doubling of your best sales day ever ends the debate.
Then it stops being a question of internal readiness and becomes a question of competitive survival, and that’s the real accelerant. The first brand in a category that posts the lift changes the math for everyone else in it. Up to that point the perceived risk is adopting too early. The instant a competitor posts the number, the risk flips, and now it’s adopting too late while they compound first-party intent data you can never go back and collect. That data asymmetry is the part that doesn’t wait. Every quarter a rival’s agent runs and yours doesn’t, they learn on shoppers you share and you fall further behind on an asset that only accumulates.
So the honest answer to what triggers deeper adoption is that it won’t be the technology finally working. The technology already works. The numbers are already on the table. It scales the moment standing still becomes more expensive than moving, and for the brands watching a competitor’s drop double its best day ever, that moment has already arrived. The roll-out doesn’t start when the industry feels ready. It starts when being last becomes the most expensive option in the room.